The Numbers on a $500K Portfolio
| Annual Cost | 10-Year Cost | What You Get | |
|---|---|---|---|
| Evernest | $47.88 | $479 | Full projection engine, 50K Monte Carlo, multiple portfolios, financial events, data tabs |
| Robo-advisor (0.25%) | $1,250 | $12,500+ | Automated portfolio rebalancing, basic retirement projections |
| Human advisor (1%) | $5,000 | $50,000+ | Personalized advice, tax planning, estate planning, ongoing relationship |
| Fee-only planner (ongoing) | $4,000–$8,000 | $40,000–$80,000 | Flat-fee financial plan, investment management, tax strategy |
| Fee-only planner (one-time plan) | $1,500–$3,000 once | $1,500–$3,000 (unless updated) | A single comprehensive plan at one point in time |
Robo-advisor and human advisor costs scale with portfolio size. On a $1M portfolio, robo-advisor fees double to $2,500/yr; human advisor fees reach $10,000/yr. Evernest stays at $47.88/yr regardless of portfolio size.
What Are You Actually Paying For?
Advisory services — whether robo or human — bundle two things together: investment management (picking and rebalancing funds) and financial planning (answering “will my money last?”). Most of the fee pays for the investment management. The planning is secondary.
But here's the thing: if you're already managing your own investments — index funds, target-date funds, a simple three-fund portfolio — you don't need to pay someone 0.25–1% of your portfolio every year to rebalance for you. What you actually want is the planning part: will my savings last, what can I spend, when should I take Social Security, what happens if the market drops.
That's exactly what Evernest does — the planning part, without the investment management fee attached.
Robo-Advisors: Paying 0.25% for What?
Betterment, Wealthfront, and similar robo-advisors charge 0.25% of your portfolio annually. On $500K, that's $1,250/year. They automatically allocate your money across ETFs and rebalance when things drift.
Some offer basic retirement projections — but nothing close to the depth of a dedicated planning tool. Most robo-advisor “retirement planning” is a probability estimate based on your age and savings rate. No Monte Carlo simulation with 50,000 scenarios. No year-by-year cash flow chart. No financial event modeling. No multiple portfolio types with independent draw strategies.
The Hidden Math
0.25% sounds small. But on a growing portfolio, it compounds against you:
Evernest costs $47.88/year no matter how large your portfolio grows. The fee never scales with your success.
What $47.88/Year Gets You
Evernest isn't an investment manager — it doesn't pick your funds or rebalance your portfolio. It's a planning tool that answers the questions you're actually paying an advisor to answer:
Monte Carlo Simulation
50,000 randomized market scenarios with full histogram output. See your probability of success, percentile breakdowns, and worst-case outcomes — the same analysis advisors charge thousands to run.
Multiple Portfolios
Model traditional, fixed income, and income investing portfolios with independent return assumptions and draw strategies. Enter your total and expected return range — no individual holdings required.
Visual Cash Flow Chart
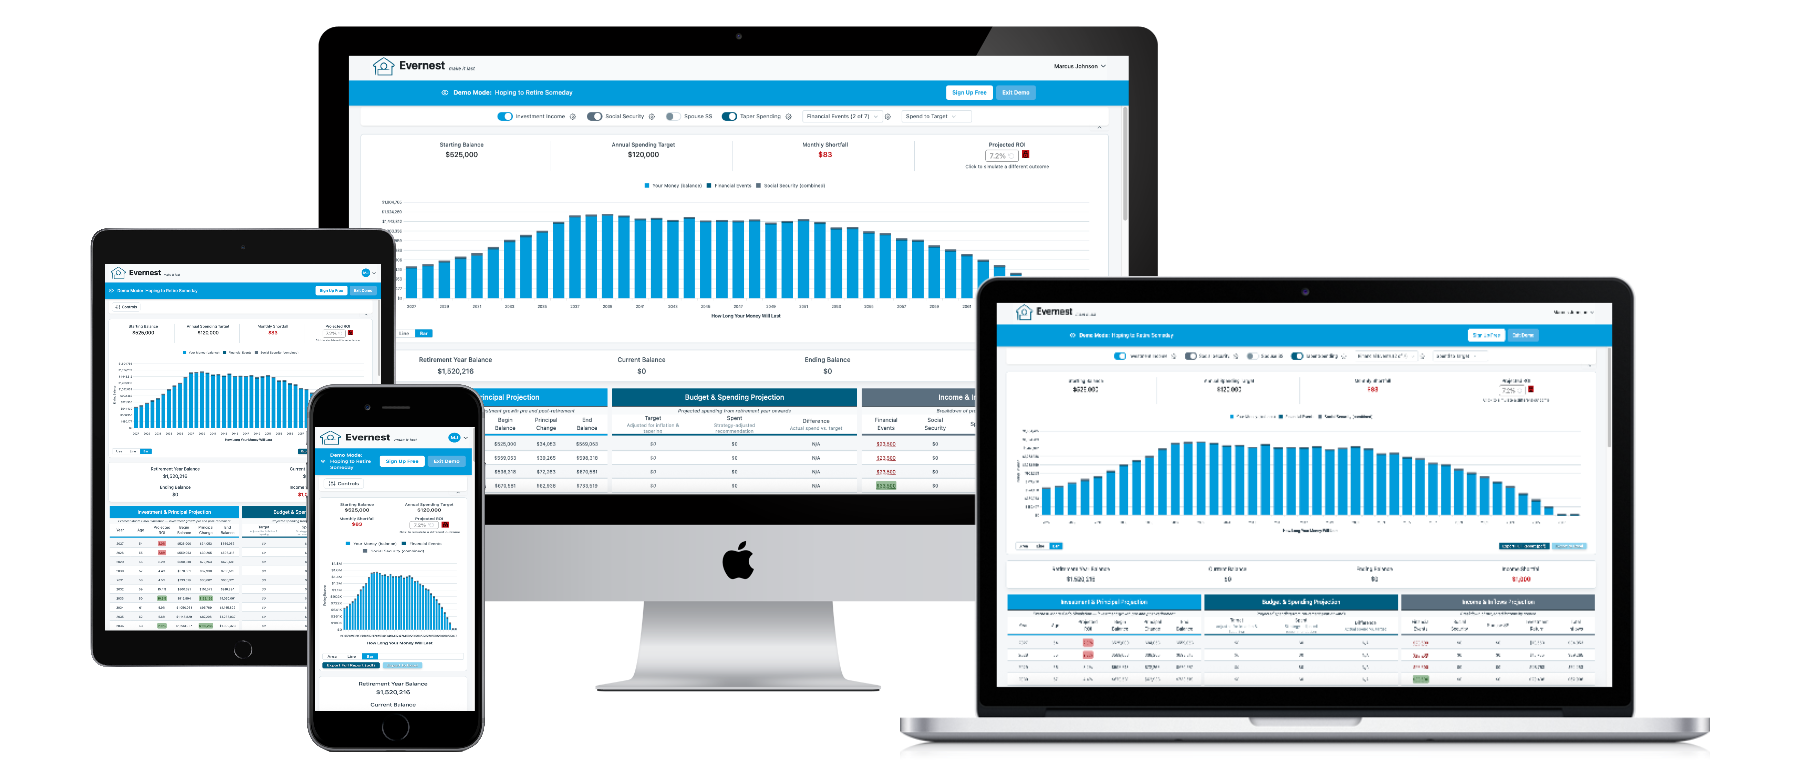
Year-by-year stacked bar chart showing exactly when money runs short, where income overlaps, and what happens when variables change. The visual answer advisors summarize in a 30-page PDF.
Financial Events
Model home sales, inheritances, college tuition, car purchases, Roth conversions — any event that changes your cash flow. See the impact instantly.
Detailed Data Tabs
Year-by-year breakdowns of every number — portfolio balances, income, spending, Social Security. The raw data behind the chart so you can verify every assumption.
Unlimited Updates
Change your assumptions anytime — new spending levels, different Social Security timing, market scenarios. No appointment needed. No waiting for your advisor to update the model.
Nobody Touches Your Money
This is a fundamental difference. Advisory services — robo or human — require access to your money. They manage your investments directly, which means they have custody of or trading authority over your accounts.
Evernest never touches your money. Never sees your accounts. Never asks for your credentials. You enter your portfolio total and expected return range, and the engine projects your money by portfolio type using historical data. Your actual brokerage accounts stay exactly where they are.
Evernest
- ✓ No access to your accounts
- ✓ No AI processes your financial data
- ✓ Nobody sees your data but you
- ✓ Delete your data permanently at any time
- ✓ We never sell your data — ever
Advisory Services
- ✗ Custody or trading authority over your accounts
- ✗ Full access to your financial data
- ✗ Data shared with custodians, clearinghouses
- ✗ Fees increase as your portfolio grows
When an Advisor Still Makes Sense
Evernest is a planning tool, not a replacement for every kind of financial advice. There are situations where professional help is worth the cost:
- •Complex estate planning: Trusts, multi-generational wealth transfer, charitable giving strategies — these require legal and tax expertise beyond any software tool.
- •Business owner transitions: Selling a business, structuring buyouts, managing concentrated stock positions — these need specialized advice.
- •One-time financial checkup: A fee-only advisor charging $1,500–$3,000 for a one-time comprehensive plan can be money well spent — especially paired with Evernest for ongoing monitoring.
- •Behavioral coaching: Some people need a human to keep them from panic-selling in a downturn. If that's you, the advisory fee may be worth it for the discipline alone.
The key question is whether you need ongoing advisory services at 0.25–1% of your portfolio every year, or whether a one-time consultation plus a $48/year planning tool gives you what you need.
The Bottom Line
Choose Evernest if:
- → You manage your own investments (index funds, target-date, etc.)
- → You want the planning without the portfolio management fee
- → You want to update your plan anytime — no appointment needed
- → You want nobody touching your accounts or seeing your data
- → You'd rather spend $48/yr than $1,250–$5,000/yr
Keep an advisor if:
- → You need estate planning or business transition advice
- → You want someone else to manage your investments
- → You need behavioral coaching to stay the course
- → You have a complex tax situation that requires ongoing professional guidance
Not Ready to Sign Up? Try a Free Calculator
Get a quick answer to your biggest retirement question — no account required:
The Same Answers. A Fraction of the Cost.
Monte Carlo simulation, multiple portfolios, year-by-year cash flow — without giving anyone access to your money. $47.88/year. No AUM fees. Ever.